

Instant Cash Advance Loan App

- 2.26K Reviews
- 4.6
- Downloads
- 1,000,000+
Our take on Instant Cash Advance Loan App from Appgk
When an unexpected bill lands between paydays, the hardest part is often not finding a long-term financial plan but finding a short-term way to cover a specific gap. Instant Cash Advance Loan App, developed by Fast Online Loans, is built around that narrow situation. I reviewed it as a finance app rather than as a general budgeting tool, and its main appeal is clear: it puts the idea of requesting a cash advance at the center instead of surrounding it with unrelated money-management features.
That focus can be useful when speed and simplicity matter more than detailed financial planning. At the same time, a borrowing app should never be treated like free money. My experience with this kind of tool is that the important question is not only whether an application feels quick, but whether the repayment terms fit comfortably into the next part of your budget. The app is most useful as a carefully considered emergency option, not as a routine way to stretch every paycheck.
What the cash-advance focus changes
The defining capability here is the attempt to make short-term borrowing feel more direct. Instead of opening a traditional banking app and searching through several products, you begin with the need for a loan. That makes the experience easier to understand for someone who already knows why they are looking for help and does not want a full suite of banking tools.
I found that this focused approach changes the decision process. The app does not encourage me to think about investing, tracking subscriptions, or building a complete household budget. It keeps attention on the immediate request. That can reduce distraction during a stressful moment, but it also means I have to bring my own judgment to the process. The app can support a borrowing decision; it cannot decide whether borrowing is sensible for my circumstances.
Best Parts of Instant Cash Advance Loan App
Things to Keep in Mind About Instant Cash Advance Loan App
The product is free to install, which removes an upfront app-store cost. That should not be confused with the total cost of borrowing. Any person considering an advance should read the applicable offer details carefully, paying attention to the amount to be repaid, timing, and any charges shown before accepting anything. A free finance app can still lead to a financial commitment once a loan is taken.
Its audience is broad in age terms because the content rating is Everyone, but that does not mean every adult is a suitable borrower. A person with irregular income, several existing repayments, or no realistic way to cover the next due date should be especially cautious. The age label describes app access, not financial readiness.
News and Features Related to Instant Cash Advance Loan App

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The practical workflow I would use
I would open the app only after writing down the exact amount needed and the date when repayment would be manageable. That small preparation makes a major difference. Without it, the convenience of a cash-advance screen can make a larger request seem harmless simply because it is available to consider.
From there, I would treat each screen as a checkpoint rather than rushing toward approval. I would confirm that my personal details are entered correctly, check the requested amount, and read every explanation connected with the offer. If the app presents several choices, I would compare the total repayment rather than focusing on the amount arriving in the account. The amount received is only half of the decision; the outgoing amount is what affects the next budget.
Don't want to read the full review?
One useful habit is to take a pause before submitting a request. If the need is a utility bill, a repair, or a medical purchase, I would first ask whether the provider offers a payment arrangement or whether a less expensive alternative exists. This is not a criticism of the app specifically. It is the most important discipline when using any fast-loan service: convenience should come after comparison, not before it.
I would also keep a private record of the request and repayment information. A screenshot or written note of the final terms can make it easier to remember what was agreed, especially when several bills are due close together. I would not rely on memory or assume that a short summary tells me everything important. The detailed offer is the part that should guide the decision.
Screenshots
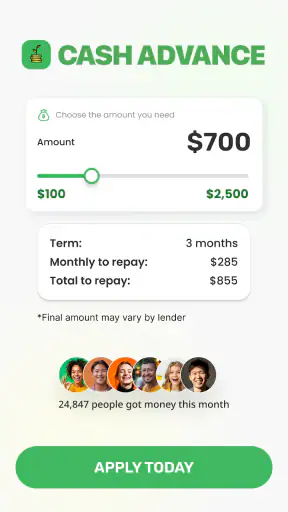
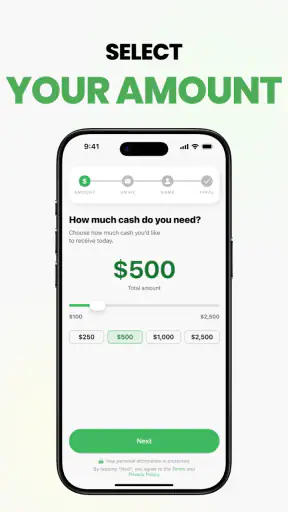
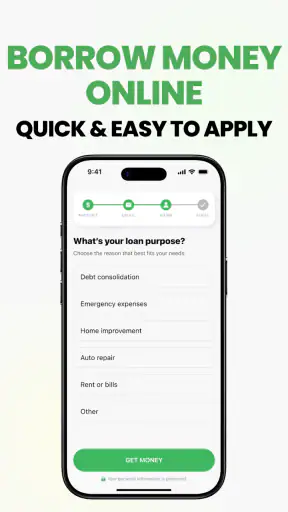
The app’s current version is 2.0.9 and it works on Android devices running version 7.0 or later. That makes it accessible to people who keep older phones, which is practical for a finance tool. Still, I would use a device with a screen lock, current security updates where possible, and a private connection. A loan request involves sensitive financial information, so convenience should not lead me to use an untrusted shared device.
A realistic emergency use case
Imagine that I need an urgent car repair to keep getting to work, but my next paycheck is still several days away. I could use the app to explore whether a cash advance might cover the repair. The sensible workflow would be to obtain the repair estimate first, request no more than the necessary amount, and compare the repayment obligation with the money already committed to rent, food, transport, and other bills.
In that scenario, the app’s central strength is not that it magically solves the expense. It gives me a direct place to investigate a short-term borrowing route while the need is clearly defined. That can be more useful than applying for a larger general-purpose loan when the gap is small and urgent.
However, the same scenario shows the boundary of its usefulness. If the repair cost is too high to repay comfortably, or if the car problem is likely to lead to more expenses, borrowing may only postpone the problem. I would then look at alternatives such as a repair payment plan, help from a trusted person, public assistance, or a lower-cost credit option. The app belongs in the comparison stage, not automatically at the end of it.
Another practical case is a temporary timing mismatch, such as a necessary household payment arriving just before regular income. Here, a short-term advance may appear reasonable if the repayment date lines up with confirmed income and the total obligation is manageable. The key distinction is between a one-off timing problem and a recurring shortage. The first may be addressed by short-term credit; the second usually needs a broader change in expenses, income, or debt structure.
Where the convenience creates friction
The strongest trade-off is speed versus reflection. A simple borrowing path is helpful when a user already understands the need, but it can also make a serious financial decision feel like an ordinary app task. I would deliberately slow down at the offer stage and avoid treating a quick application as a quick solution.
Another limitation is that a focused loan app is not a replacement for a full personal-finance system. I would not expect it to show me whether a new repayment fits alongside all my other obligations. That calculation remains mine. Anyone who wants spending categories, savings goals, debt snowball planning, or a complete view of several accounts may be better served by a budgeting app or their existing bank.
There is also a difference between being able to submit a request and receiving money on terms that make sense. An application can be convenient without guaranteeing that the result will match the amount or timing I want. I would avoid making a purchase based on the assumption that an advance will arrive until the relevant process is complete and the terms are understood.
For the same reason, I would not use this app to cover another loan payment unless I had examined the full chain of repayments. Moving one obligation into another can create a cycle that feels manageable at first and becomes difficult later. The app’s cash-advance focus is most defensible when it addresses a defined, temporary expense—not when it is used to keep an ongoing shortfall hidden.
Privacy is another area where I would stay attentive. Finance apps require a higher level of care than entertainment apps because the information involved can be sensitive. I would review the app’s on-screen explanations and permissions before continuing, keep the phone protected, and avoid sharing login or personal details with anyone claiming to “help” with the application. These habits are valuable regardless of the provider.
How it compares with ordinary alternatives
Compared with a traditional bank loan, this app’s appeal is its narrower, more immediate orientation. A bank may be the better route for a larger planned expense, a longer repayment period, or an existing customer who wants everything managed in one place. A bank relationship may also make it easier to review broader account activity and regular income. The trade-off is that the process can feel less direct than opening a dedicated cash-advance app.
Compared with a credit card, the choice depends on the terms and personal habits. A card can be convenient for a purchase and may offer a familiar repayment system, but it can also encourage spending beyond the original need. A cash-advance request makes the borrowing purpose more explicit, which I consider a useful psychological boundary. Neither option is automatically cheaper; I would compare the complete repayment cost and timing.
Compared with borrowing from a trusted friend or family member, the app offers privacy and a formal digital process. Personal borrowing may avoid some costs, but it can strain relationships and create uncomfortable uncertainty if expectations are not written down. The app avoids that interpersonal issue, while introducing its own contractual and financial responsibilities.
Compared with a budgeting app, this product solves a different problem. A budget can help prevent the emergency from recurring by showing where money is going and how much can be set aside. This app is aimed at the immediate borrowing question. If I were repeatedly opening it because the same shortage returned each month, I would regard that as a signal to use budgeting support or debt advice instead.
Who benefits most from this focused design
The best fit is an adult who has a clearly defined short-term expense, understands that borrowing must be repaid, and can identify a realistic source of repayment. That person may appreciate the app’s direct finance category, its free installation, and its emphasis on exploring a cash advance without navigating a large banking ecosystem.
The app has attracted substantial attention, with more than a million installs and an average rating of 4.6 from around fifty-two thousand ratings. Those figures suggest that many people find the basic experience useful, but they should not replace personal evaluation. A popular borrowing app can still be unsuitable for someone whose income or existing debts make another repayment unsafe.
I would recommend it more readily to someone comparing options for a one-time timing gap than to someone searching for a permanent income supplement. It may also suit people using an older Android phone, since the minimum operating-system requirement reaches back to Android 7.0. That accessibility is convenient, although device security remains important when handling financial information.
I would tell a friend to skip it if they are unsure how they will repay, need money for discretionary shopping, are already missing payments, or are considering borrowing simply because the request feels easy. In those situations, the right next step is usually to reduce the immediate cost, negotiate the bill, seek qualified financial guidance, or examine a lower-cost alternative.
My final view after weighing the use case
Instant Cash Advance Loan App does one thing clearly: it gives short-term borrowing a direct place in the app experience. That is its real value. The design makes sense when I have a specific emergency, a known amount, and a credible repayment plan. It is less convincing as a general financial companion because it does not replace budgeting, debt planning, or careful comparison.
Fast Online Loans has positioned the product for people who want to investigate a cash advance without paying to install the app, and the strong user response shows that the approach resonates with a large audience. Still, I would judge the app by the terms attached to a particular offer, not by its popularity or the speed suggested by its name.
My recommendation is therefore conditional but positive: use Instant Cash Advance Loan App as a focused comparison tool for a genuine, temporary need, and read the repayment details before committing. If the numbers fit comfortably after essential expenses, its direct approach can save time. If the repayment would depend on another loan, a hoped-for windfall, or skipping necessities, I would choose a different solution. In short, the app can make a borrowing option easier to examine, but it cannot make borrowing affordable when the budget says otherwise.
Instant Cash Advance Loan App FAQ
What is the Instant Cash Advance Loan App, and how does it work?
The Instant Cash Advance Loan App is designed to let eligible users apply for a short-term cash advance from a mobile device. After creating an account, you generally provide personal, employment, and banking information so the service can review your application. If approved, the requested amount may be deposited into your linked bank account, although approval, timing, and availability depend on the provider’s policies.
Who can use the Instant Cash Advance Loan App?
Eligibility requirements can vary, but applicants typically need to meet minimum age and residency conditions, have a valid government-issued identification document, and maintain an active bank account or debit card. Some services may also require proof of regular income or employment. Before downloading, check the app’s official eligibility rules because installing the app does not guarantee approval or access to funds.
How much does the service cost, and are there any hidden fees?
The total cost depends on the loan provider, the amount borrowed, repayment period, and the selected funding option. Possible charges may include interest, origination fees, subscription costs, late-payment penalties, or an optional expedited-transfer fee. Review the annual percentage rate, finance charges, repayment schedule, and all disclosures carefully before accepting an offer, and avoid any service that does not clearly explain its costs.
How and when must an advance be repaid?
Repayment is usually scheduled for a specific date or dates shown in the loan agreement. The app may automatically withdraw the payment from your linked bank account or debit card, while some providers allow manual repayment through the application. Processing times can differ between banks. Make sure the account contains enough money on the due date, because failed payments may lead to additional fees or other consequences.
Is the Instant Cash Advance Loan App safe to use?
Safety depends on the specific developer, lender, and permissions requested by the application. Download it only from an official app store, verify the publisher’s identity, read recent user reviews, and inspect the privacy policy before submitting sensitive information. Be cautious if the app requests unnecessary access, promises guaranteed approval, or asks for an upfront payment before explaining the complete loan terms.











